

BILL Spend & Expense (Divvy) analysis by Appwee
I approached BILL Spend & Expense as a work tool rather than something I would open casually. Its purpose is clear: it brings corporate cards and expense management together in one mobile experience. That combination matters because business spending usually becomes frustrating at the handoff between making a purchase, proving why it was made, and getting the record into the right place.
In my experience, the app makes the strongest first impression when I treat it as part of a repeatable spending routine. I can imagine opening it after a work lunch, a taxi ride, a software purchase, or a trip-related expense instead of leaving receipts scattered through email, pockets, and camera-roll folders. It is a free Business app from Bill.com Inc., and its Everyone content rating makes it broadly approachable for employees who need a practical way to handle company spending.
The bigger question is not whether the app sounds useful during the first week. Most expense tools do. The real test is whether it earns a permanent place on a phone after the novelty disappears. That depends on how consistently a team uses its corporate-card process, how disciplined employees are about recording purchases, and whether the organization benefits from keeping card activity and expense work together.
What the first week feels like
The first week is where the central idea becomes easy to understand. A corporate card is not only a payment method; it also creates a trail that someone eventually has to review. An expense-management app can reduce the gap between those two things, especially for people who buy items away from their desks. Instead of thinking of expenses as an end-of-month chore, I find it more natural to deal with them close to the moment of purchase.
A realistic example would be a small team member attending a client meeting. They pay for transportation and a meal with the company card, then use the app while the details are still fresh. That timing is important. The merchant, purpose, and business context are easier to remember immediately than several weeks later, when the employee is trying to reconstruct a busy day from a bank statement.
This is where the app’s mobile focus earns its place. A desktop-only process may work for planned purchases, but it is less convenient when spending happens between meetings or while travelling. I would use the phone as the capture point and treat the later review process as a separate task. That division keeps the employee moving without pretending that every transaction deserves a long session at the moment it happens.
The app is also likely to feel more useful to a team than to a lone freelancer who simply wants a personal spending tracker. Its identity is built around company spending, so the value increases when several people need a shared, consistent process. If your work expenses are rare and easy to reimburse manually, the setup may feel heavier than the problem you are trying to solve.
One practical tip is to establish a personal rule before the first business purchase: finish the expense while the receipt is physically or digitally available. That small habit is more valuable than installing the app and hoping it will rescue an entire month of neglected records. The software can organize a workflow, but it cannot reliably recreate context that the user never recorded.
The current version is 4.0.17, and the minimum operating-system requirement is 12. That makes checking device compatibility an important first step for anyone using an older iPhone or iPad. I would also ask a team to test the complete path with one ordinary purchase before moving all spending into the system. A short trial can reveal whether employees understand what they are expected to submit and whether managers can review the resulting information comfortably.
Where the early appeal comes from
The first-week appeal comes from reducing the number of places where expense information lives. Without a dedicated process, a receipt may sit in a wallet, an inbox, a text message, or a notes app while the card transaction appears somewhere else. Combining corporate-card activity with expense management gives a business a better chance of connecting the purchase to its explanation before the details fade.
I especially like the idea of using the app at the edge of the workflow rather than waiting for accounting time. The person who made the purchase has the best knowledge of its purpose. A manager reviewing it later may understand the broad context but still need to ask basic questions if the original employee left everything until the end of the month.
There is also a useful psychological benefit: a visible, repeatable routine makes company spending feel less mysterious. Employees know that a card purchase is not finished simply because the payment went through. Managers can think about review as an ongoing responsibility instead of a sudden administrative pileup.
That said, I would not mistake a tidy mobile workflow for automatic accuracy. A transaction can still be assigned the wrong purpose, submitted without enough context, or overlooked by someone who assumes the card feed handles everything. The app helps most when the organization agrees on what “complete” means for each purchase.
Why the value can last from month to month
After the first month, the question changes from convenience to consistency. The lasting value of BILL Spend & Expense is not one impressive interaction; it is the reduction of repeated friction across many ordinary purchases. A team that uses corporate cards regularly can benefit from making expense handling part of the same routine as spending itself.
For a manager, the advantage is easier follow-up. Instead of waiting for employees to remember every purchase during a reporting deadline, the manager has a process to review as spending occurs. For an employee, the advantage is less reconstruction later. These are modest improvements individually, but they compound when a business has several people making purchases every week.
The app’s public reception suggests that it has found an audience: it carries an average rating of 4.5 from around 4.3 thousand ratings, with over 100 thousand installs. I read that as evidence of sustained interest rather than proof that every company will find the workflow perfect. Business apps are unusually dependent on internal habits, approval expectations, and the way a company already handles its financial records.
A useful monthly routine would be to reserve a short review window each week rather than waiting for a deadline. Employees can check that recent card activity has the necessary explanation, while managers can spot questions before they become urgent. This is a non-obvious strength of a mobile expense tool: it can move administrative attention closer to the event that created the record.
Another good practice is to separate two decisions that people often mix together. First, ask whether the purchase was appropriate for work. Second, ask whether the record contains enough information for someone else to understand it. A legitimate purchase can still be badly documented. Treating documentation as its own step makes the system more useful for audits, budgeting discussions, and internal accountability.
I would also avoid turning every employee into a finance specialist. The app works better when the organization gives simple guidance around recurring situations: meals, travel, client-related purchases, subscriptions, and small office items. Clear examples reduce back-and-forth messages and prevent every person from inventing a different interpretation of what should be recorded.
Who gets the most recurring value
The strongest fit is a company where multiple employees use corporate cards and someone needs a dependable view of the resulting expenses. Sales teams, travelling staff, project groups, and distributed workplaces are natural candidates because purchases happen away from a central office. The app can also help a growing business that has outgrown informal receipt collection but does not want employees juggling several disconnected tools.
It is less compelling for someone who only tracks personal spending, since corporate-card and business-expense workflows are central to its purpose. I would also hesitate if your organization has no agreed owner for reviewing submissions. A tool cannot fix an undefined responsibility. If everyone assumes someone else will check the records, the app may simply create another place for unfinished work.
Companies with highly specialized accounting, procurement, or compliance requirements should evaluate the whole workflow before committing. The question is not only whether employees can enter expenses. It is whether the information produced fits the organization’s existing review and bookkeeping process without creating duplicate work. In that situation, a more specialized platform may be a better choice even if this app feels simpler on the phone.
The maintenance burden behind the convenience
Every expense app has a maintenance cost, and this one is no exception. The burden is not necessarily technical; it is behavioral. Employees must remember to use the app, keep their explanations clear, and respond when a manager needs clarification. Managers must review activity regularly instead of allowing unresolved items to accumulate.
That maintenance is manageable when the company treats the process as part of normal work. It becomes tiring when the app is introduced as a one-time fix for years of disorganized spending. I would set expectations before rollout, including when employees should update an expense and who handles questions. A short written policy paired with a simple demonstration is more useful than assuming the interface will teach the entire process.
There is also a device-maintenance angle. Since the app requires operating system 12 or later, older devices may need attention before a team can use it consistently. In a mixed-device workplace, compatibility should be checked early rather than discovered when one employee cannot participate. That kind of small obstacle can undermine adoption even when the underlying workflow is sound.
Another maintenance issue is review fatigue. If managers open every transaction with the same level of scrutiny, the process may become slow and discouraging. A better approach is to define what deserves immediate attention and what can be reviewed in a regular rhythm. The app can centralize the work, but the organization still needs sensible judgment about priorities.
I would also keep the distinction between a record and a receipt in mind. A card transaction tells the business that money moved; an expense record should explain the business reason clearly enough for another person to follow. Employees who only rely on the existence of the transaction may believe they are finished too soon. The lasting benefit comes from pairing the payment trail with useful context.
Small habits that prevent large cleanups
My preferred habit would be a “close the loop” check after each work outing. Before moving on, I would confirm that the purchase has been recognized, described, and left in a state that another reviewer can understand. This takes less effort than reconstructing a full day of spending later and makes the app part of the event rather than an afterthought.
For frequent travellers, batching can be tempting, but I would use it carefully. Grouping several expenses into one later session may save a few minutes in the moment, yet it increases the chance of confusing merchants, dates, or purposes. A better compromise is to capture the essential details promptly and reserve a weekly session for checking the overall record.
For managers, I recommend looking for patterns rather than merely clearing a queue. Repeated unclear descriptions may indicate that employees need better examples. Frequent late submissions may point to a workflow problem rather than individual carelessness. This is one of the app’s less obvious long-term uses: the expense process can reveal where company instructions are unclear.
For employees, the most useful mindset is to write for a future reader. “Dinner” may make sense today, but “client meeting dinner” or another accurate business explanation gives the reviewer more context. I would not add invented detail, but I would avoid descriptions so vague that they create another question.
Where fatigue begins
The first source of fatigue is repetition without visible payoff. If an employee enters the same kind of information after every purchase but never receives feedback or sees a smoother review process, the routine can feel like paperwork added to paperwork. Managers need to demonstrate that timely submissions actually reduce follow-up and end-of-month pressure.
The second is unclear ownership. A corporate-card system touches employees, managers, and finance staff, so confusion at any handoff can make the app feel responsible for a problem that is really organizational. Before adopting it, I would map one purchase from payment to final review and identify who acts at each stage. That exercise often exposes missing instructions earlier than a full rollout would.
The third is overuse. Not every minor question needs a complicated approval ritual, and not every employee needs the same level of oversight. If a company turns the app into a rigid barrier for ordinary spending, people may delay entries or search for workarounds. The best experience balances control with speed.
There is a trade-off between centralization and flexibility here. Keeping corporate-card and expense information together can make the process easier to follow, but it may feel restrictive to organizations that already have a mature system built around other tools. Switching only makes sense if the combined workflow removes more friction than it introduces.
I also would not choose it solely because it is free. The absence of a purchase price for the app does not remove the cost of training, policy design, review time, and adoption. A company should judge the total workflow, not just the download decision. If the team will not use it consistently, a free tool can still be an expensive distraction.
Compared with paper receipts and spreadsheets, this approach is more immediate and better suited to employees who spend away from a desk. Compared with a general personal-finance app, it is more relevant to company-card accountability. Compared with a deeply specialized finance platform, it may appeal to teams that value a focused mobile routine over a broad, complex system. The right comparison depends on the problem: scattered evidence, weak review habits, or advanced financial operations are not the same challenge.
My long-term verdict
After the novelty fades, BILL Spend & Expense earns lasting space when a business makes it the normal place to handle corporate-card activity and expense follow-up. Its recurring value comes from timing: the closer an employee records a purchase to the moment it happens, the less work remains for everyone else. That is a simple idea, but it addresses one of the most persistent weaknesses in business spending.
I would recommend it to a team that wants employees and managers to share one practical mobile routine, especially when spending happens on the road or across several locations. The free price and Everyone rating make it easy to consider, while the broad adoption and 4.5 average provide some reassurance that it is not an obscure experiment. Still, I would make the decision based on workflow fit rather than popularity.
I would skip it if you need a personal budgeting app, if your company rarely uses corporate cards, or if your existing finance system already handles the same process smoothly. I would also pause if nobody has time to define expectations and review activity. In those cases, the app may be perfectly reasonable but still wrong for the organization.
My final assessment is positive but practical. This is not a tool I would install for novelty; I would install it to create a habit. The habit succeeds when employees close the loop promptly, managers review without unnecessary friction, and the company treats expense documentation as part of spending rather than a separate monthly emergency. Its real strength is the routine it can support, not the promise of effortless administration.
For readers deciding whether to try it, I would begin with one team and one ordinary spending cycle. Check how quickly employees understand the process, how many follow-up questions managers need to ask, and whether the records are easier to review than the current method. If those answers improve, the app has earned a place in the wider organization. If they do not, a different business-expense solution may be the wiser long-term choice.
Gallery
BILL Spend & Expense (Divvy) Pros and Cons
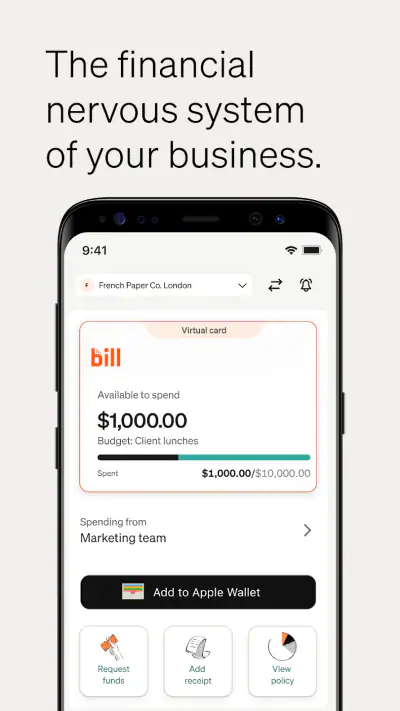
- Real-time spending visibility helps teams monitor budgets as purchases happen.
- Virtual cards can reduce exposure when paying online or with unfamiliar vendors.
- Receipt capture makes it easier to keep transaction records organized.
- Custom spending limits support tighter control over employee purchases.
- Useful reporting tools can simplify reviews of department and project expenses.
- Some features may require an eligible business account or administrator setup.
- The app is less useful for individuals managing only personal expenses.
- Approval workflows can feel restrictive for urgent or unusual purchases.
- Syncing transactions may occasionally depend on bank or card processing delays.
- Advanced controls may take time for smaller teams to configure properly.
BILL Spend & Expense (Divvy) Frequently Asked Questions
What is BILL Spend & Expense (Divvy), and who is it designed for?
BILL Spend & Expense, formerly known as Divvy, is a business spending and expense-management app designed for companies, finance teams, managers, and employees. It helps organizations issue and manage corporate cards, create spending budgets, track transactions, collect receipts, and simplify expense reporting. It is generally more useful for businesses using the BILL platform than for individuals seeking a personal budgeting app.
Can employees use BILL Spend & Expense to submit receipts and expenses?
Yes. Employees can typically use the app to review card transactions, upload or photograph receipts, add notes and expense details, and submit information for approval. The exact workflow depends on how the employer has configured policies, budgets, approval rules, and accounting integrations. Users should also check whether their company requires receipts for specific purchases or spending categories.
Does BILL Spend & Expense include corporate card and budget management features?
A major purpose of BILL Spend & Expense is to give businesses more control over company spending. Administrators can generally create budgets, assign spending limits, monitor transactions, and manage employee or department expenses from the BILL platform. Available card features, controls, and permissions may vary according to the company’s plan, eligibility, region, and relationship with BILL.
Is BILL Spend & Expense free to download and use?
The mobile application may be available to download without an upfront charge, but downloading the app does not necessarily mean that the overall service is free. BILL Spend & Expense is primarily a business platform, and pricing, account requirements, corporate card availability, and included features are determined by BILL and the organization’s agreement. Employees should confirm access with their employer before downloading.
Is BILL Spend & Expense safe for managing business transactions and receipts?
BILL Spend & Expense is built for business expense workflows and uses account authentication and organizational permissions to help control access to financial information. Nevertheless, users should protect their login credentials, enable available security options, avoid uploading sensitive documents unnecessarily, and use the latest official app version. Security also depends on company policies, administrator settings, device protection, and responsible user behavior.














